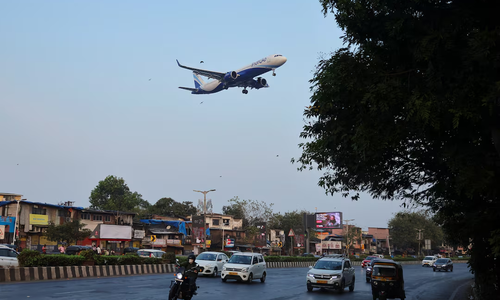
Shares of IndiGo rose on Friday as investors looked past a fuel-hit quarterly loss and focused on what the airline is doing to protect its profitability. Fare hikes, capacity discipline and network optimisation are the three levers that put the stock back in favour.
How the stock moved?
IndiGo was up roughly 3% at ₹4,810 as of 9:37 a.m. IST, its highest level in two weeks. The benchmark Nifty 50 was up 0.22% at the same time, so the airline’s gain outpaced the broader market.
The quarter in context
India’s largest airline posted its third consecutive quarterly loss. The picture was not entirely negative, though. The loss narrowed from a year earlier because revenue growth and higher fares partly offset rising costs.
The pressure point was fuel. It made up nearly 38% of IndiGo’s total costs and rose sharply along with global oil prices. For an airline, that is the line item that can swing a quarter, and this one was no exception.
Why investors are not panicking?
Analysts say elevated fuel costs will continue to weigh on earnings, but they see three factors that can limit the damage: tight industry capacity, resilient fares and IndiGo’s own cost-management efforts. Together, these keep the longer-term profitability outlook intact.
Here is how individual brokerages read the results:
- Jefferies called the quarter largely in line with expectations. It pointed to resilient pricing and to management’s guidance for low single-digit capacity growth in the current quarter.
- Ambit Capital said the earnings upgrade cycle has not yet started. It did note favourable supply-demand dynamics and IndiGo’s work on its fleet and network, including a gradual reduction in expensive damp-leased wide-body aircraft.
- Emkay Global named fuel costs as the key thing to watch. It said fare hikes, premiumisation initiatives and network adjustments should support earnings, since industry capacity remains constrained.
In simple terms, when fewer seats are available across the industry, airlines have more room to hold or raise fares. That is the cushion analysts are counting on while fuel prices stay high.
What the analyst consensus says?
The average rating from 25 analysts covering IndiGo is “buy”, with a median price target of ₹5,700, well above the current price.
The year so far
Even after Friday’s gain, the stock has lost 5% so far this year. That compares with a 12% fall in the Nifty 50 over the same period, which means IndiGo has held up better than the broader market in a difficult year.
What to watch next?
The key variable is fuel. If global oil prices stay elevated, the pressure on margins will continue, and the airline will need its fare and cost measures to keep working. Capacity growth guidance and progress on fleet and network changes will also be closely tracked.
Note for readers: This article is for information only and is not investment advice. Please consult a qualified financial adviser before making investment decisions.
Frequently Asked Questions
Why did IndiGo shares rise on Friday?
- Investors looked past the fuel-hit quarterly loss and focused on the airline’s efforts to protect profitability through fare hikes, capacity discipline and network optimisation.
How much did IndiGo’s stock gain?
- The stock was up roughly 3% at ₹4,810 as of 9:37 a.m. IST, its highest level in two weeks.
What were IndiGo’s quarterly results?
- IndiGo posted its third consecutive quarterly loss, but the loss narrowed from a year earlier as revenue growth and higher fares partly offset rising costs.
How much of IndiGo’s costs come from fuel?
- Fuel made up nearly 38% of total costs and rose sharply with global oil prices.
What do analysts say about IndiGo?
- The average rating from 25 analysts is “buy”, with a median price target of ₹5,700. Brokerages such as Jefferies, Ambit Capital and Emkay Global point to resilient pricing, tight industry capacity and cost management as supports for earnings.
How has IndiGo’s stock performed this year?
- It has fallen 5% so far this year, compared with a 12% drop in the Nifty 50.