Africa Holds the Minerals the World Needs for Clean Energy. So Why Is It Capturing So Little of the Value?
A World Bank-commissioned study says fragmented policies and limited processing are leaving Africa’s mineral wealth on the table, and argues that working together is the way out.
Key Takeaways
- The opportunity: African countries hold deposits of 41 minerals used in electric vehicles, batteries, solar, wind and grids.
- The problem: Most countries export these minerals raw or lightly processed, so the biggest profits are made elsewhere.
- The dependence: China absorbed over 40 per cent of Africa’s annual mineral ore exports.
- The proof: Congolese cobalt sells for US$5.80 per kg at extraction, and US$16.20 per kg after local refining.
- The fix: The researchers argue for deeper regional cooperation, shared infrastructure and coordinated policies.
Why the Green Transition Runs on Minerals?
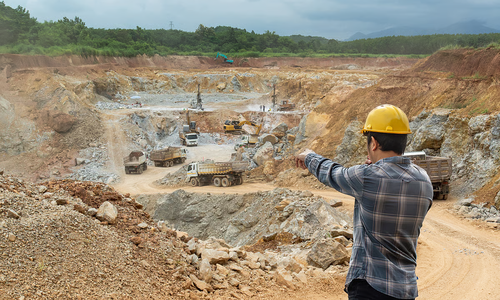
Clean energy sounds light, but the technology behind it is heavy on raw materials. Electric vehicles, batteries, solar panels, wind turbines and power grids all rely on minerals such as cobalt, lithium, copper, manganese, graphite and rare earths.
The International Energy Agency estimates that an electric car needs six times more minerals than a petrol or diesel car. A wind power plant needs about nine times more minerals than a gas-fired plant.
As countries speed up their shift to cleaner energy, demand for these materials keeps rising. Africa, which has deposits of several of the minerals involved, should be well placed to benefit.
But there is a catch that many resource-rich developing countries know well. Having minerals in the ground does not automatically create industries, jobs or shared prosperity. The study behind this story starts from that uncomfortable point.
What the Study Set Out to Find?
The research was led by economists who study how countries build industries. Its authors are Gideon Ndubuisi (Delft University of Technology), Elvis Korku Avenyo (University of Johannesburg), Solomon Owusu (Boston University) and Woubet Kassa (American University). The work was commissioned by the World Bank.
Their question was simple: how far have African countries moved beyond simply digging up the minerals the energy transition needs? Are they refining them, or making components for green technologies?
They worked in four steps:
- Identified which transition minerals each African country has.
- Studied trade data to see who exports these minerals and where they are sold.
- Looked at where African countries sit in green-technology value chains, whether they only mine and export, process the material, or make finished products like solar panels.
- Reviewed national and regional mineral and industrial policies.
Africa’s Mineral Strength Is Real
The scale of the continent’s endowment is striking.
- African countries hold deposits of 41 minerals used across bioenergy, electricity networks, batteries, energy storage, electric vehicles and carbon capture. They are also wanted for fuel cells, hydrogen, geothermal, heat pumps, hydropower, nuclear, solar and wind power.
- 48 African countries have deposits, reserves or production of at least one transition mineral.
- South Africa has 24 of the 41 minerals. Nigeria and the Democratic Republic of Congo (DRC) each have 14.
- Across the continent, Africa holds about 96 per cent of global platinum group metal reserves, 77 per cent of phosphate reserves and 55 per cent of cobalt reserves.
Phosphate and cobalt are used in electric vehicle batteries, while platinum is used in technologies that produce and use green hydrogen.
The Catch: Strong Together on Paper, Weak Apart in Practice
Here is where the picture changes. While Africa as a whole is powerful, most countries individually account for only a small share of any given mineral.
Trade data shows this clearly. Apart from South Africa, Nigeria and the DRC, most African countries export less than 1 per cent of each mineral globally. For minerals such as nickel, rare earths, silver and lithium, the five largest African exporters together supply less than 10 per cent of world exports.
Why does this matter? Small national volumes make it harder for a single country to influence buyers, attract large processing plants, build complete supply chains or compete with established producers elsewhere.
Could Countries Coordinate Their Trade Policies?
The researchers suggest that coordinating trade policy, instead of acting separately, could strengthen Africa’s position. There is a legal wrinkle, though. Private companies hold mining licences, and permission to extract does not always come with an unrestricted right to export. That may give governments some room to coordinate trade rules.
The authors are careful here. How this would work alongside companies’ existing rights, and whether it would need their agreement, still needs further study.
Where the Value Leaks Out: Processing?
The study describes limited local processing as a deeper weakness. Processing happens mainly in a few countries, including South Africa, the DRC, Zambia and Zimbabwe. Even there, the work often means crushing and concentrating ore, not making products from the mineral.
The cobalt example shows what is at stake. Congolese cobalt can sell for US$5.80 per kilogram at the point of extraction. After local refining, the price rises to US$16.20 per kilogram, nearly tripling its value.
That gap is the value Africa loses each time raw material leaves the continent before it is refined.
A Green Economy Built on Old Dependencies
The trade patterns will look familiar to anyone who has followed the history of commodities.
- Asia, and China in particular, is the leading importer of 16 minerals from Africa. It took over 30 per cent of those exports on average and was the second-biggest buyer of six other transition minerals.
- China absorbed over 40 per cent of Africa’s annual mineral ore exports.
The researchers say this shows Africa repeating an old pattern: mining raw materials while other countries turn them into more valuable products.
The same story shows up in technology. Between 2017 and 2023, Africa’s global patent share across the green technologies studied stayed below 0.4 per cent, and its export share was below 1 per cent in every category. In the authors’ words, African countries currently take part in the green economy more as consumers than as producers.
The study links this to history and low industrialisation. As a result, the wealth in the ground has not yet translated into high levels of industrial activity, well-paid jobs, higher incomes or wide improvements in living standards.
African Governments Are Not Standing Still
The report does not paint governments as passive. Many are changing mining laws, restricting exports, taking ownership stakes and forming partnerships to gain more from their minerals. The goal is to keep more processing, investment, jobs and income at home.
Most of these efforts are happening country by country, though some governments are working together across borders. National and regional institutions are taking steps, but the researchers say most initiatives are still at an early stage.
Going it alone has clear limits:
- Many countries supply too little to influence large international buyers. If one government demands higher prices or local processing, buyers can shop elsewhere.
- Many also lack reliable electricity, affordable loans, transport and skilled workers, all of which are needed to process minerals and make components.
What the Researchers Say Needs to Happen?
The central argument is that Africa is strong in minerals as a continent, and should act like one. The report points to a related study, Integrating Africa: From Threads to Hubs, whose central thesis is that deeper regional cooperation helps countries build industries, not just trade more easily with each other.
Their recommendations include:
- Pool resources. Combining mineral supplies, markets, infrastructure and skills could lower costs and strengthen negotiating power with global companies.
- Build shared processing hubs. A processing centre serving several countries would help the whole continent.
- Agree on common rules. African finance and mineral institutions and national governments need shared priorities and similar rules on how minerals are processed and how environmental damage is managed.
- Use development finance. Regional development banks and other African financiers could fund shared electricity, transport and mineral-processing infrastructure, while universities and businesses build the technical skills these industries need.
- Rethink foreign partnerships. Deals with foreign governments and companies should go beyond extraction and export. They should include commitments to process more minerals in Africa, share technology and know-how, train workers and help local firms become suppliers to new green industries.
Our Analysis: What This Means
The following is editorial analysis, not reported fact.
The most useful way to read this report is as a story about bargaining power, not geology. Africa’s reserves are not in doubt. What the data shows is that the continent’s strength exists mainly in aggregate, while decisions are still made country by country.
The cobalt price gap is the clearest signal. When refining alone nearly triples the value of a mineral, every tonne exported raw carries a hidden cost.
The report also raises a practical question for policymakers: cooperation on paper is easy, but shared electricity, transport and processing plants require money and trust across borders. That is why the emphasis on development finance and common rules matters as much as the headline call for unity.
What to Watch Next?
- Whether more African governments move from acting alone to coordinating trade and processing policy.
- Whether development banks fund shared processing and infrastructure projects.
- Whether foreign partnerships begin to include commitments on local processing, technology sharing and training.
- Whether processing expands beyond crushing and concentrating ore into higher-value products.
Frequently Asked Questions
How many transition minerals does Africa have?
- African countries have deposits of 41 minerals used across clean energy technologies, according to the World Bank-commissioned study. At least one is found in 48 African countries.
How much of the world’s cobalt does Africa hold?
- Africa holds about 55 per cent of global cobalt reserves. It also holds about 96 per cent of platinum group metal reserves and 77 per cent of phosphate reserves.
Why is Africa not benefiting more from its minerals?
- Most countries export minerals raw or lightly processed. Individually, most account for only small global shares, and many lack reliable electricity, affordable loans, transport and skilled workers.
How much more is cobalt worth after refining?
- Congolese cobalt can sell for US$5.80 per kg at extraction. After local refining, it sells for US$16.20 per kg, nearly triple the price.
What role does China play?
- China absorbed over 40 per cent of Africa’s annual mineral ore exports. Asia, with China in particular, is the leading importer of 16 minerals from Africa.
What does the report recommend?
- Deeper regional cooperation: pooling mineral supplies, markets, infrastructure and skills, building shared processing centres, agreeing common rules and using development finance to fund shared infrastructure.
How much of the green-technology market does Africa have?
- Between 2017 and 2023, Africa’s global patent share across the technologies studied stayed below 0.4 per cent, and its export share was below 1 per cent in every category.
Africa has the minerals the energy transition depends on. What it lacks, according to this study, is the coordination, infrastructure and processing capacity to keep more of the value at home. The researchers’ answer is not to stop mining, but to move up the value chain together.